When budgets are tight or when income is modest, people often learn to stretch every euro, value every purchase, and avoid waste. But many of these habits aren’t only for those who “have to”, they’re useful for anyone wanting to build wealth or stabilize finances. The middle class can adopt frugal habits not as deprivation, but as strategies for financial security and freedom. Here are fifteen practices worth learning from those who live frugally.
Track every expense and income
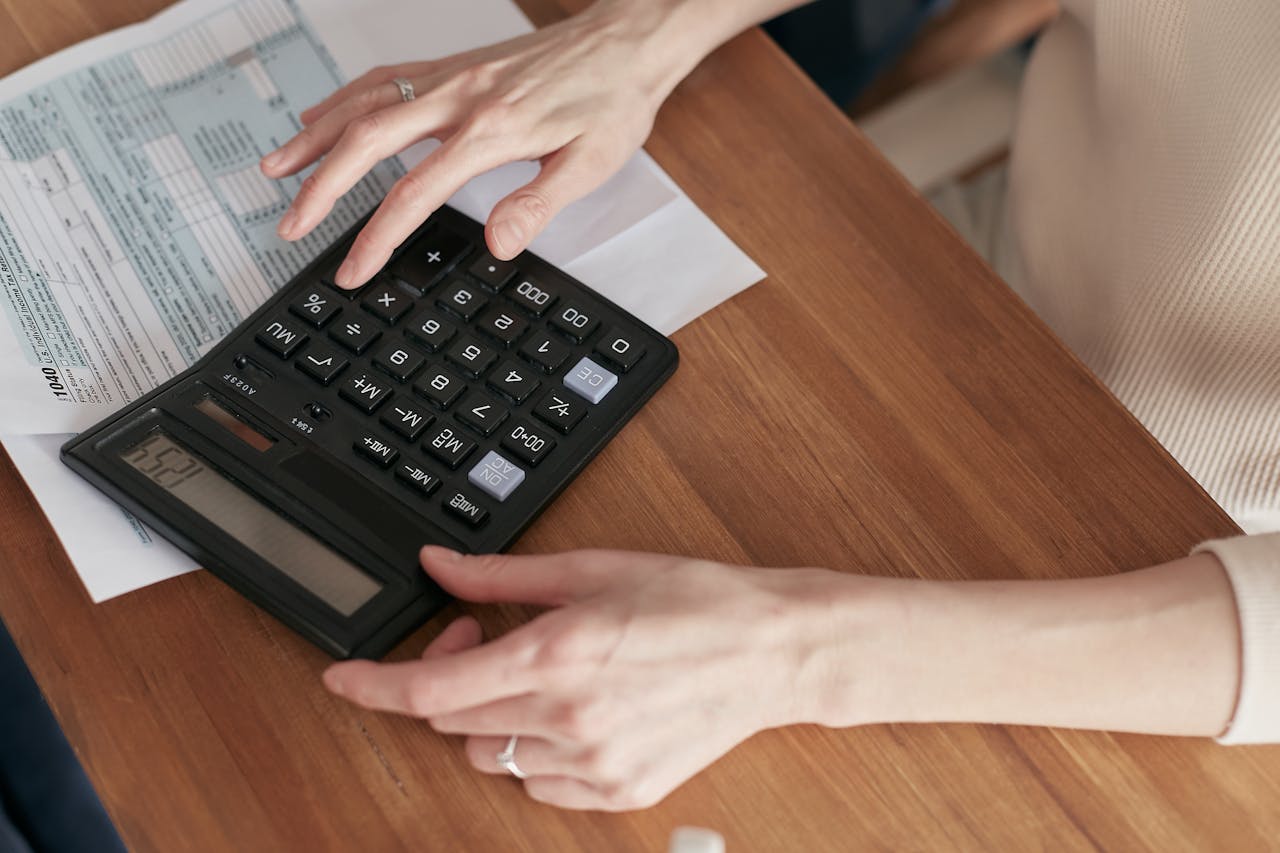
Frugality starts with awareness: knowing exactly where your money comes from and where it goes. Recording every expense, from bills to small coffee purchases, reveals patterns and areas of leakage. Using budgeting apps or simple spreadsheets helps. When income is known and expenses visible, decision-making becomes easier and more intentional. You avoid surprises and can see opportunities to redirect spending into saving or investing.
Set goals and priorities
Frugal people often have clear goals: paying off debt, building emergency savings, investing, or reaching financial independence. These goals help them make trade-offs, deciding whether a purchase aligns with long-term goals or is just a whim. Prioritizing what matters (family, health, education, future freedom) reduces regret over spending. When you know what you’re aiming for, it’s easier to say “no” to what doesn’t support your goal.
Live below your means
Perhaps the most common habit: spending less than you earn. Even when income rises, frugal individuals often resist lifestyle inflation (buying more just because they can). They avoid letting outward signs of success (a bigger house, a newer car, and fancy clothes) drive spending beyond what they can easily afford. This gap between earnings and spending is what allows savings, investment, and flexibility.
Avoid debt-depending consumption
Credit cards, loans for non-essential items, buying on credit to project status, these are habits many frugal people avoid. If debt is used, it’s for appreciating assets (real estate, business), not for consumption. Paying off credit balances each month, not carrying high interest, helps avoid interest drains. Staying mindful of interest rates and being cautious about borrowing for wants rather than needs preserves long-term financial health.
Bulk buying and meal planning
Buying non-perishable items in bulk reduces per-unit cost; planning meals prevents waste and reduces reliance on takeout. Frugal households often plan meals for the week, write shopping lists, and buy staples when they’re on sale. This also helps minimize trips to grocery stores, lessening impulse buys. By knowing what ingredients you have, you waste less and eat better.
Reuse, repair, repurpose
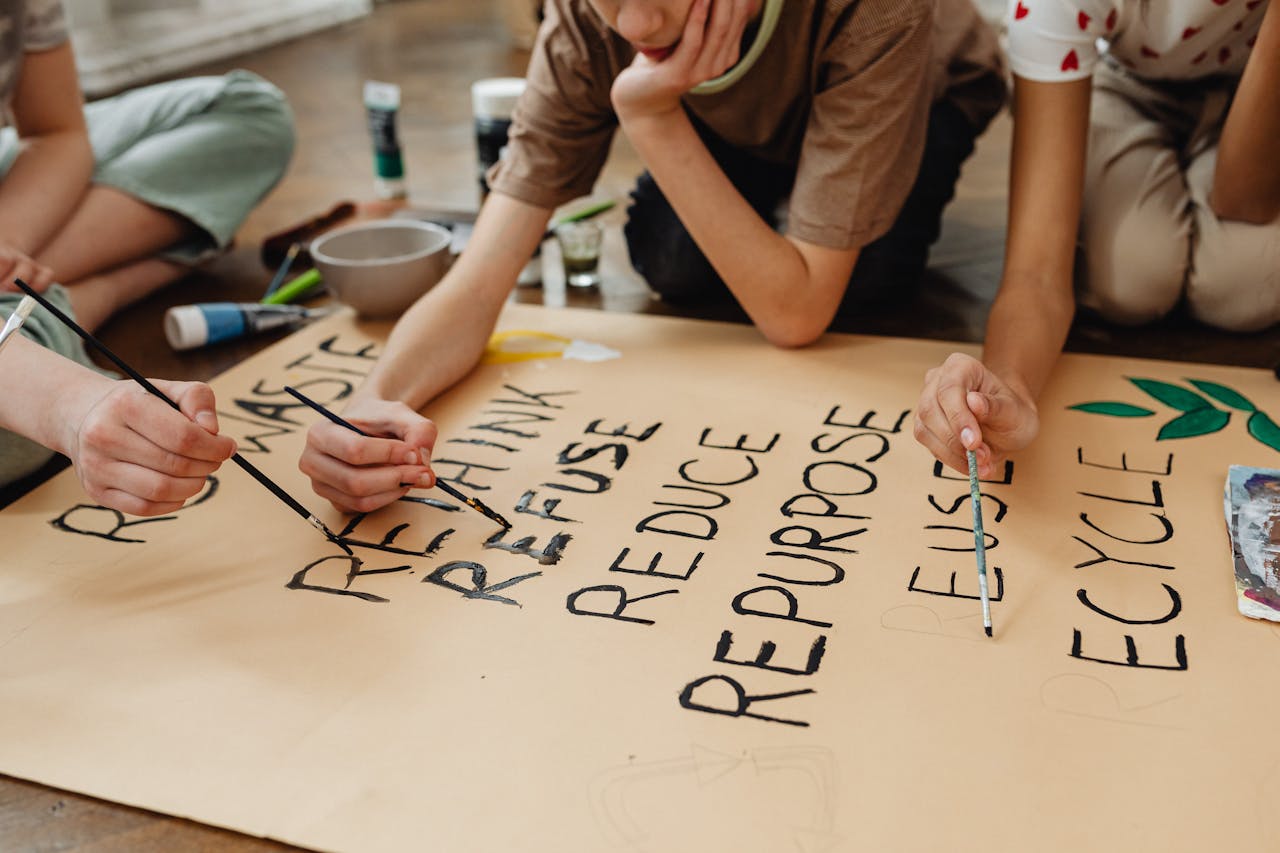
Instead of discarding something that’s broken or worn, frugal people often repair. Shoes, appliances, clothing can sometimes be mended or refurbished. Repurposing items extends life and reduces purchasing frequency. Even small repairs (replacing a zipper, sewing a hem) add up over time. This habit fosters sustainability and reduces regret from wasteful consumption.
Delay purchases and embrace waiting periods
Before buying something non-essential, frugal individuals might wait 24 hours or more, or put it on a list and revisit. That cool-down helps reveal whether the desire was genuine or impulsive. It also gives time to research, compare prices, and find better deals. Often, once time passes, the urge fades, saving money and regret.
Buy quality over brand hype
Rather than chasing labels, frugal people look at durability, materials, warranty, and repairability. A well-made product that lasts many years often costs less per year of use than a cheap item replaced quickly. Sometimes paying more up front is smarter than constantly replacing. This applies to clothes, electronics, furniture, tools, etc.
Use free or lower-cost entertainment
Frugal habits include choosing entertainment that’s low cost: libraries, parks, community events, free concerts, hiking, reading, or streaming library services. Instead of costly outings or continuous subscriptions, they gravitate toward what brings joy for little, or no, cost. Also, using public or shared resources is common. This builds enjoyment without high recurring bills.
Meal prep and home cooking
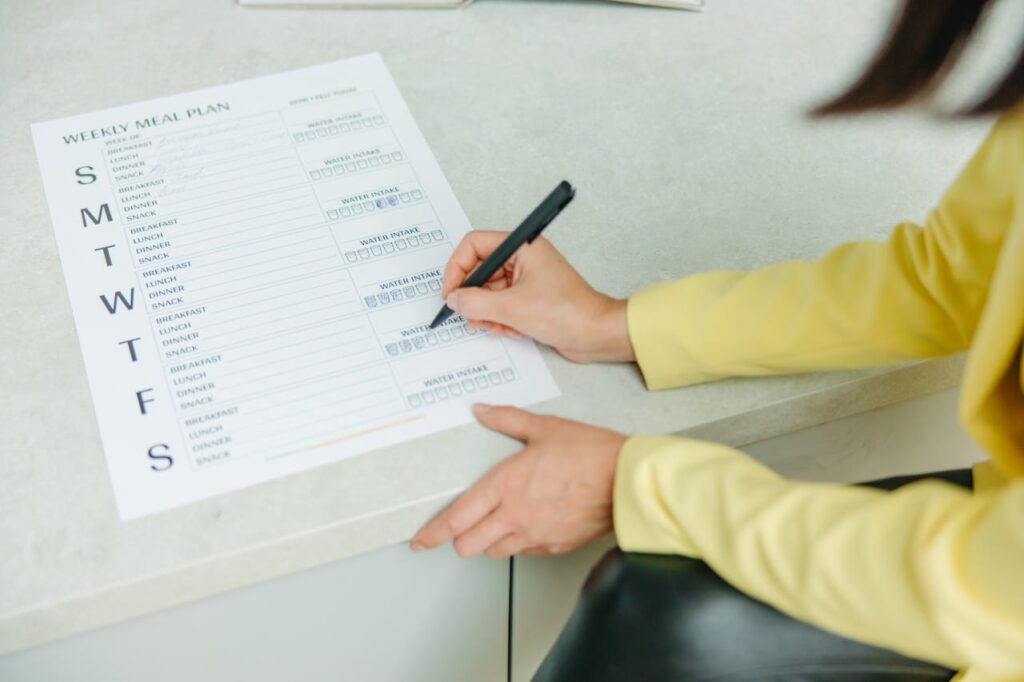
Cooking at home produces cost savings over eating out, and lets you control nutrition, portions, and waste. Preparing meals in advance (batch cooking) makes it easier on busy days. Frugal households might cook extra for leftovers. This habit tends to improve health too, as processed or fast-food meals are often less nutritious. Shopping with meal plans also helps you avoid impulse ingredient buys.
Regular saving and automated investment
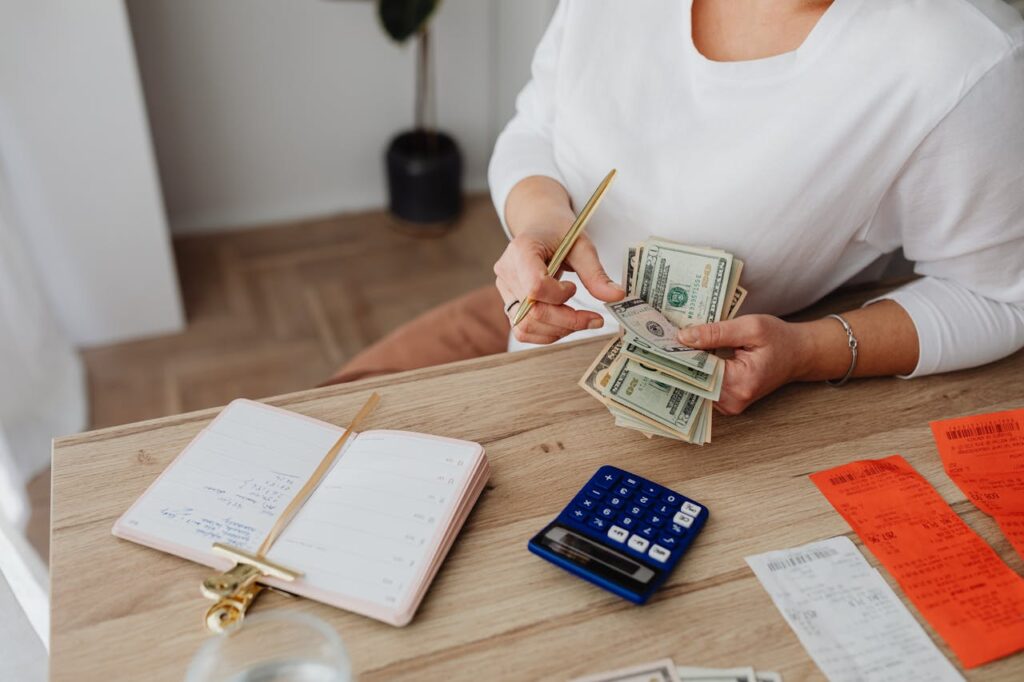
Rather than saving whatever’s left, frugal people often pay themselves first: automatic transfers to savings or investment accounts the moment income arrives. They treat savings as a bill that must be paid. Over time, compounding helps grow those savings. This builds discipline and reduces temptation to spend what you hadn’t mentally designated.
Shop with a list and comparison
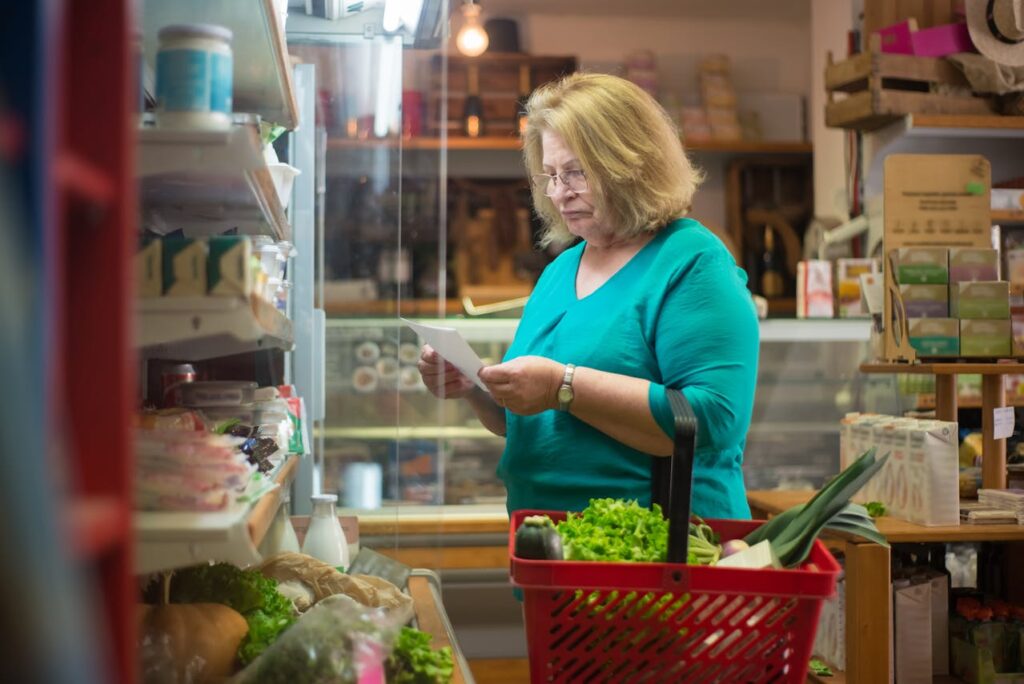
Before going shopping, groceries, clothes, appliances, frugal people make lists. They compare stores, check for sales, discount codes. They might buy off season, buy used or refurbished, or join loyalty or rewards programs. All this helps avoid overpaying. Small savings repeatedly add up.
Reduce recurring costs
Subscriptions, utility bills, insurance premiums, service fees, all recurring costs that often slip under the radar. Frugal people review these regularly, cancel what isn’t used, negotiate where possible, or switch provider. For example, they might compare insurance quotes or reduce energy use. Recurring cost reductions reduce overhead and free up income.
Side hustles or additional income streams
To increase financial stability, many frugal middle-class people also try to build supplementary income streams, part-time freelance work, selling things, tutoring, online services, or investing. Even modest extra income can accelerate savings, reduce debt, or allow more flexibility. Diversifying income reduces dependence on a single paycheck.
Cultivate contentment and gratitude
This habit is less tangible but powerful: being satisfied with what you have, avoiding constantly comparing to others, finding joy in simple pleasures. Gratitude reduces the urge to spend for show. Contentment makes budgeting less burdensome because one feels less deprived. It anchors decisions around lasting fulfillment, not just accumulation of more stuff.